I can see why business owners would want an AI agent to handle their payments.
You receive invoices, check the amounts, match them against completed work, enter everything into your accounting software and finally make the transfers. It's repetitive administrative work, and most of it follows fairly predictable rules.
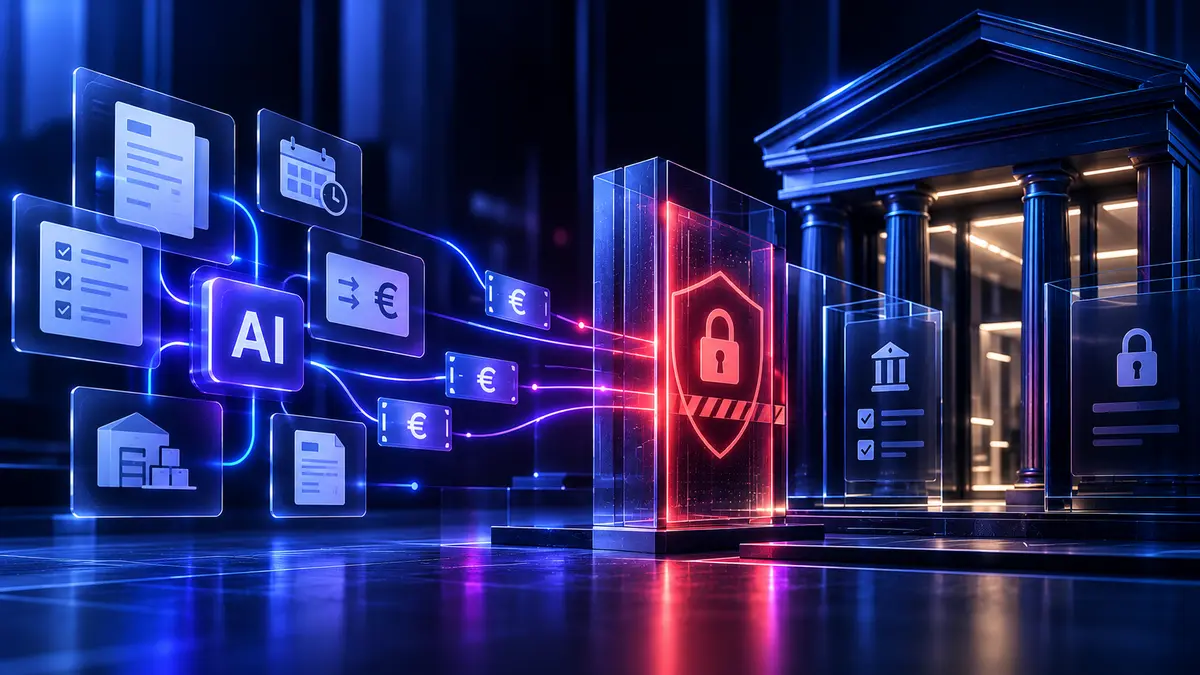
An AI agent could take care of a significant part of that process. But there's a difference between preparing a payment and having permission to move money out of someone's bank account. That's where banks are starting to push back.
What actually happened
According to The Times, Bank of England governor Andrew Bailey has warned about unresolved questions surrounding autonomous AI agents and financial transactions.
The concern is fairly straightforward. If an AI agent independently transfers money, who is legally responsible for that decision? The person who owns the account? The company operating the AI? The financial institution that processed the transfer?
Existing financial regulations weren't designed around software that can independently interpret instructions, make decisions and initiate transactions.
The warning comes alongside reported restrictions by major US banks, including Citigroup and Bank of America, on AI-agent access to customer accounts.
Financial institutions are also concerned about the possibility of agents rapidly moving money between banks, creating new operational and financial stability risks. For businesses developing autonomous financial workflows, these restrictions could become a practical obstacle.
Why a small team cares
Consider a freelance consultant who works with several subcontractors.
Every month, invoices arrive from designers, developers and other service providers. The consultant needs to check each invoice, verify that the work was completed, record the expense and arrange payment.
It's easy to imagine an AI workflow handling almost everything up to the final transfer. It could monitor an invoice inbox, extract information from PDFs, check amounts against agreed budgets and prepare payment requests in the accounting system.
If something looks unusual, it could flag the invoice for review. Once everything is verified, the consultant could approve the payments through their normal banking interface. That would already save meaningful administrative time.
I'd be much less comfortable giving the same agent direct access to the bank account and allowing it to independently authorize transfers.
A misunderstood instruction, duplicate invoice or incorrect account number could result in a real financial loss. And if the automation relies on controlling a banking website through a browser, it could stop working whenever the bank changes its interface or access restrictions.
For a small business, a single expensive mistake could wipe out months of savings from automation.
Hype vs useful
There's a lot of excitement around agents that can complete entire business processes, including making payments. I think we'll eventually see useful implementations of this, particularly as payment providers introduce more structured ways for agents to initiate transactions.
But I wouldn't build a business-critical payment workflow around unrestricted AI access to a banking website today.
The immediate opportunity is in the administrative work surrounding payments. Reading invoices, extracting data, checking suppliers, reconciling expenses and preparing transfers are all tasks where AI can reduce manual effort without needing complete control over the business's money.
Existing payment providers already have systems for authorization, transaction limits and audit trails. Using those systems makes considerably more sense than trying to recreate financial controls inside an AI workflow.
For now, I would measure the success of a financial agent by how much accurate, verifiable admin it removes. It doesn't need to press the final payment button to earn its place.